
For brokers working with real estate investors, a successful fix-and-flip deal doesn’t have to be the end of the relationship.
Some borrowers will always want to renovate, sell and move on to their next project. But others might be sitting on a property that could be more profitable as a long-term rental.
For those borrowers, refinancing from a fix-and-flip loan into a debt service coverage ratio (DSCR) loan could give them a way to hold onto the property, generate rental income and keep building their portfolio.
Knowing how to spot those opportunities can turn a single transaction into a much longer client relationship. The key is knowing which deals are suited to a DSCR exit, when to raise the possibility and how to make sure the conversation is driven by the borrower’s goals.
In this guide, we’ll look at how brokers can identify potential DSCR refinance opportunities among their existing fix-and-flip clients in New York and New Jersey: and help those clients decide what comes next.
Start the refinance conversation before the renovation is done
The best time to bring up a DSCR refinance is long before the fix-and-flip loan is reaching maturity. By then, the borrower may already be committed to selling, or working against the clock to arrange their next move.
Instead, start thinking about the exit strategy from the beginning of the deal. Even if the borrower plans to sell, understanding their longer-term plans gives you an opportunity to introduce refinancing as another potential route without asking them to make a decision upfront.
As the renovation progresses, revisit the conversation. The midpoint of the project can be a useful checkpoint as there’s usually a clearer picture of the finished property, its potential value and what it could achieve in rent.
The borrower’s plans may have changed, too. Rental demand might be stronger than expected. The property could be performing better than originally projected. Or a borrower who initially planned to sell may decide they’d rather keep the asset and expand their rental portfolio instead.
Learn to spot DSCR-ready flips
Not every successful fix-and-flip project will make a successful rental. The key is to look beyond the quality of the renovation and think about whether the finished property is likely to work as a long-term investment.
Start with the renovation itself
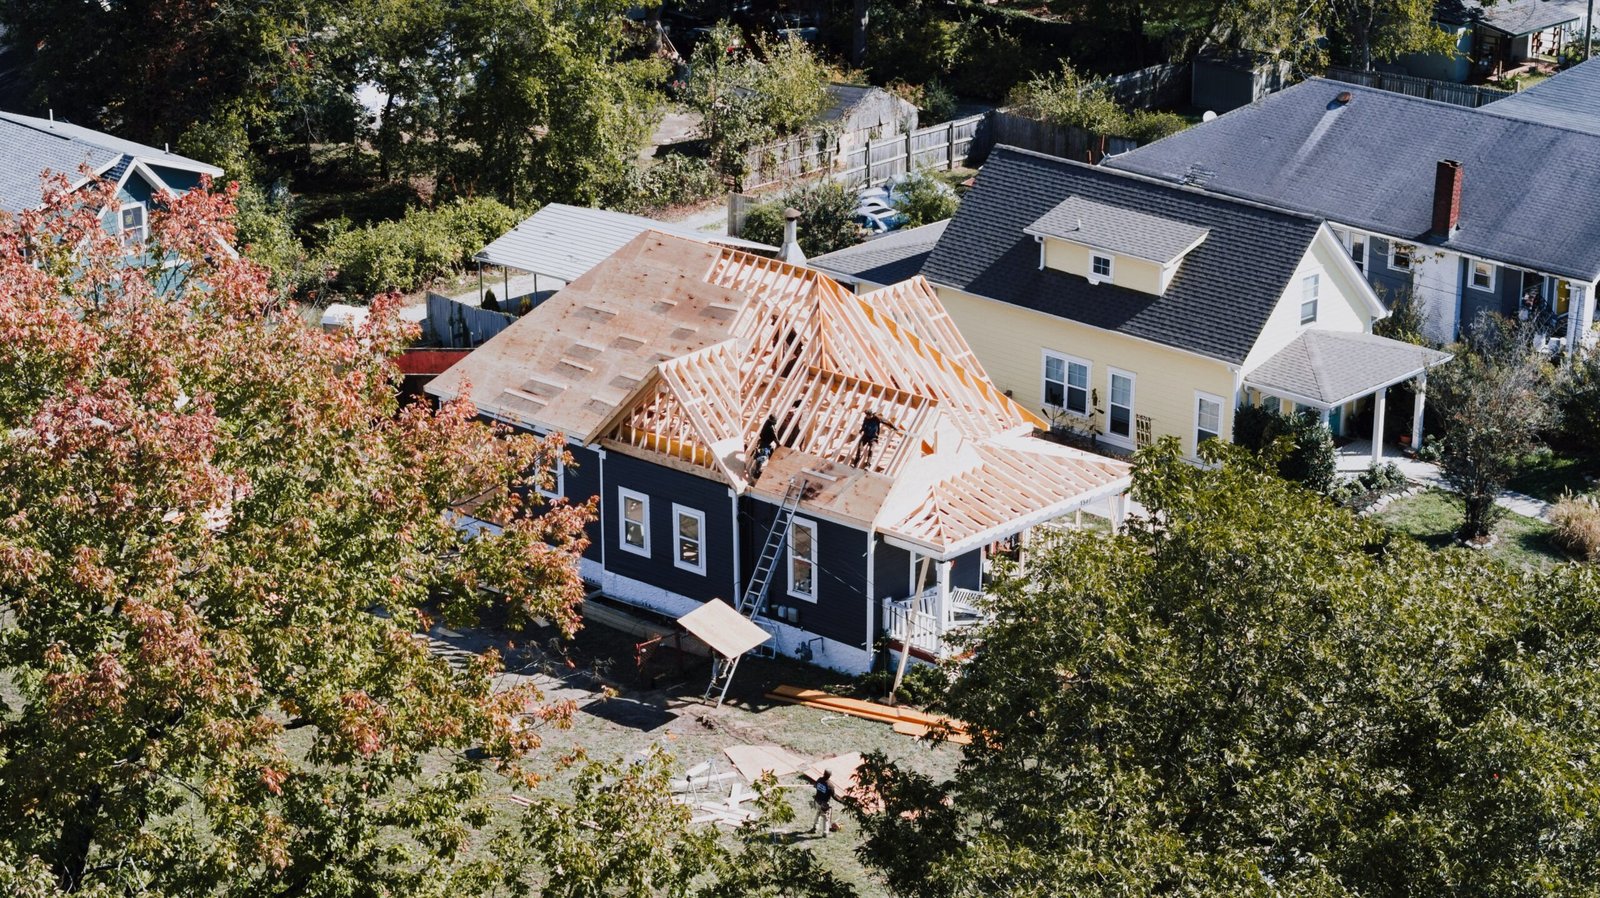
Some improvements can increase both the property’s resale value and its rental potential. Work that improves the property’s condition, functionality and durability (such as updating kitchens and bathrooms, replacing outdated systems or addressing deferred maintenance) can leave a borrower with an asset that’s ready to rent without a lot of extra work.
For more on what this looks like, read our article about improving your DSCR through strategic property improvements.
More specialized or high-end renovations may point more naturally toward a sale, especially if the borrower needs a high resale price to make the project viable.
Crunch the numbers
Look at the property’s expected value once renovations are complete and compare it to the rent it could (realistically) command. If the rental income can support the proposed DSCR financing, and the borrower has enough equity in the finished property, refinancing is worth exploring.
Our DSCR Calculator gives you that read in minutes, without working the math by hand between calls. Run it early, then again as the renovation nears completion. If a deal looks close but not quite there, check with your Express Capital Financing loan officer, since requirements can vary by deal structure and there may be more flexibility than the numbers alone suggest. Worth confirming seasoning requirements too, since some lenders base a cash-out refinance on the property’s improved value only after a minimum ownership period.
Take location into account
In New York, higher property values in some markets can translate into larger loan amounts, while more affordable upstate markets may give investors opportunities to acquire and refinance multiple properties as they build a portfolio. Brokers can explore DSCR loans in New York to see what financing options may be available.
In New Jersey, closeness to major employment centers and strong renter populations can create opportunities for investors converting renovated properties into long-term rentals. New Jersey DSCR loans can help eligible borrowers make the transition from short-term financing to a longer-term rental strategy.
Wherever the property is located, the fundamentals still need to work. Local rents, property values, taxes, insurance and other expenses can all affect whether a property supports the required DSCR, so the opportunity should always be assessed on a deal-by-deal basis.
Look at the borrower as well as the property
Someone who wants to build a long-term portfolio, generate rental income or keep hold of appreciating assets is a more natural candidate for a DSCR conversion than an investor whose strategy depends on quickly recycling all their capital into the next flip.
As well as asking “could this property sell for a profit?” also think “could this property work harder for the borrower if they kept it?” Asking both questions can help you identify the flips where a DSCR refinance deserves a closer look.
Understand the long-term value of the relationship
It’s important to look beyond further than the commission on a single refinance and think about the potential value of the borrower’s wider strategy: how many properties are they planning to acquire, how quickly do they expect to complete their projects, and how many could ultimately become rentals?
Take a borrower completing four fix-and-flip projects a year. If they sell all four, each transaction comes to a natural end. But, if one or two properties are suitable for a DSCR refinance, those same projects can create extra opportunities without the broker having to find a new client.
Deal speed is important here, too. A borrower who refinances a finished property may be able to release capital for their next acquisition while keeping the existing asset. Over time, that can create a cycle of acquisitions, renovations and refinances across New York and/or New Jersey, with the broker involved at multiple stages.
Rather than steering a borrower toward whichever option generates the largest commission, this strategy seeks to understand the financing available in each market well enough to identify the route that supports the borrower’s plans.
Turn individual transactions into a repeat-client pipeline
The real value of a successful DSCR refinance is what can happen next.
A fix-and-flip borrower who sells a property might come back to you when they’re ready to fund their next acquisition. But helping that same borrower add a rental to their portfolio creates another financing touchpoint, and gives you a better understanding of where they want to go next.
Over time, that creates a repeatable cycle:
Fix-and-flip acquisition → renovation → DSCR refinance → next acquisition → repeat
As the borrower’s portfolio grows, so does the relationship. You’ll have more in-depth knowledge of their investment strategy, the types of properties they’re targeting and when they’re likely to need financing. Instead of waiting for the next enquiry to arrive, you can start anticipating where you may be able to help.
That familiarity makes future conversations more efficient. You already get how the borrower operates, and they know they have a broker who can help them consider both short-term financing and longer-term exits.
This is where a strong relationship with the right private lender can make a difference. Working with a lender that understands your client’s strategy across different stages of the investment cycle can help you find solutions as their needs change: from acquiring their next project to refinancing a finished property into their rental portfolio.
Make it advice, not an upsell
A DSCR refinance should only be part of the conversation if it makes sense for the borrower. Not every fix-and-flip client will want to become a landlord, but it’s important to make sure they understand all the options available.
Start with asking about their plans rather than leading with a product. Throughout the renovation, questions like “what do you want this property to do for you?” or “have you considered what it could achieve as a rental?” can open up the conversation without assuming refinancing is the right answer.
You can then explore the practical considerations together. Does the borrower need the money from a sale to fund their next project? Would refinancing release enough capital to keep them moving? Are they interested in generating longer-term rental income? And does holding the property fit with the portfolio they ultimately want to build?
In some cases, selling will still make more sense. In these cases, it’s important to say that. Borrowers are more likely to value a broker who helps them weigh up their options than one who appears to be looking for another transaction.
Position the DSCR conversation as part of good exit planning: “Before you put the property on the market, let’s look at what selling and refinancing would each mean for your next move.”
That keeps the borrower’s goals at the center of the conversation. And whether they choose to sell or refinance this time, you’ve shown that you’re thinking beyond the current deal: giving them a reason to come back when they’re ready for the next one.
Build the refinance check into every fix-and-flip deal
Not every fix-and-flip should become a rental, but every deal is worth a discussion about what comes next.
By building a refinance checkpoint into your fix-and-flip process, you can identify the properties and borrowers where a DSCR exit deserves a closer look. Raise the option early, understand the borrower’s longer-term goals and compare refinancing with selling before they commit to their next move.
For the right borrower, that could mean keeping a valuable asset, generating rental income and taking another step toward a larger portfolio. For you, it’s an opportunity to keep supporting that client as their investment strategy evolves from one project to the next.
Express Capital Financing works with brokers across New York and New Jersey to finance both fix-and-flip projects and long-term rental investments. If you have a client approaching the end of a renovation, talk to our team about whether a DSCR refinance could be the right next step.